Contents
You’ve got water on the floor. You call your insurance company, and before you hang up, they’ve already got a name for you. A restoration company they “work with.” It sounds easy. One less call to make on a bad day.
Here’s what most homeowners don’t realize: that company’s customer is the insurance company, not you.
We’ve never been on any insurance company’s preferred vendor or referral program, and that’s on purpose. Here’s what you should know before you say yes to whoever your insurer sends.
Who does the preferred vendor work for?
Most of our customers call their insurance company first, just to confirm their coverage and that they can choose who does the mitigation. That’s where a lot of people go wrong. The insurance company will usually try to send its preferred vendor, a company that works for them, not you.
That matters because of who’s paying attention to what. In our experience, insurance companies want to negotiate every job down, no matter how fair the price is. A company that gets its work from the insurer has every reason to keep the insurer happy.
We’ve never worked for an insurance company. On a claim, we work for you, the homeowner, because working for the insurer too would be a conflict of interest. You’re our customer, and we always try to keep your best interest in mind.
Can you choose your own company in Florida?
Often, yes. But whether it costs you anything comes down to your policy, so read it before you sign with anyone. That includes us.
Some Florida policies have what’s called a managed repair program. Citizens Property Insurance has one. It covers water damage that isn’t from the weather, like a plumbing leak, an AC overflow, or an appliance that let go. Citizens says the program is your choice. But its own program materials say that if you skip its free emergency water removal and hire your own company, coverage for that emergency work can be capped at $3,000, minus your deductible. And if you don’t use its contractor network for the permanent repairs, the claim falls under a $10,000 limit.
Other insurers write it differently. Some have their own managed repair language. Some just cap water damage at a flat amount. A lot of policies now cap water mitigation at $3,000, and that puts homeowners in a tight spot when a medium water job runs $3,000 to $8,000.
Florida’s Homeowner Claims Bill of Rights tells you to contact your insurance company before you sign any repair contract to confirm any managed repair provisions in your policy. That’s good advice. Every policy is different, so check yours or ask your agent. When you call, ask two things:
- Does my policy let me choose who does the mitigation?
- What’s my coverage if I do?
We can’t promise what your insurance will pay. That’s between you and your carrier. What we can do is document everything so your claim is backed up.
The red flag we see most in Brevard
The biggest thing we see locally is insurance companies’ preferred vendors coming in from Orlando, Fort Pierce, Fort Lauderdale, even New Smyrna. Too often, their techs don’t know where water hides in a house, and they leave it wet. Then we get the call for the mold.
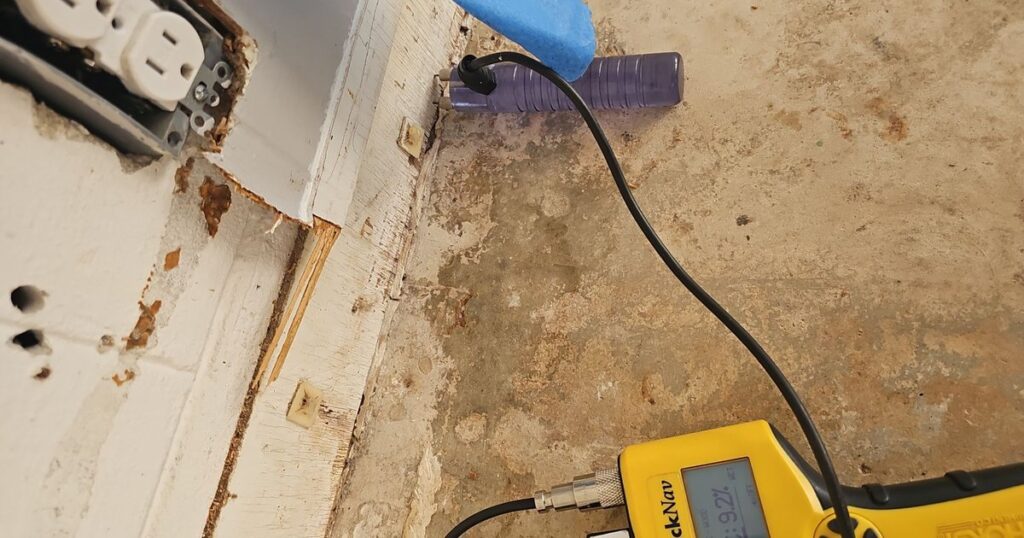
That happens when the mitigation isn’t done right in the beginning, and it means more headaches and a longer timeline for you. Water wicks up into the drywall, the bottom plate of the wall that sits right on the slab, and the particle board in your cabinets. Mop up what you can see and leave the rest, and mold can start growing within 24 to 48 hours.
Pick the right company first.
How we work when insurance is involved
We contract directly with you, the homeowner. We take a deposit before every job starts. Sometimes it’s 50% of the job, sometimes it’s your deductible. At the end of the day the bill is yours, even if your insurance company doesn’t pay for some reason. That’s the hard truth.
Here’s why we do it that way. Working directly for you means the job gets done right instead of to the insurer’s budget.
We document everything the way insurance companies want it, and we write our estimates in Xactimate, the same software their adjusters use. On every job, we take a “dry standard” reading on a wall the water never touched, so we’re drying your house back to your own home’s numbers, not a made-up one. Normally the insurance company pays you and you pay us, or you pay us and get reimbursed for the completed work.
On most of our insurance claims, we refer a public adjuster to help our customer get everything their policy covers and recover as much as possible from the insurance company, so they have the money to put their home back together properly.
Questions to ask before you hire anyone
Whether the name came from your insurance company, a neighbor, or a Google search, ask these first:
- Who do you work for, me or my insurance company?
- Are you local?
- Are you licensed for mold remediation in Florida?
- Does your insurance specifically cover mold?
- How will you know my home is dry?
- Who pays for the clearance assessment?
A good company won’t mind any of them.
Quick answers
Do I have to use the restoration company my insurance recommends? Not always. It depends on your policy. Some policies, like those with Citizens’ managed repair program, can limit your coverage if you go with your own company. Check your policy or ask your agent before you sign anything.
Who does an insurance company’s preferred vendor work for? The insurance company. That’s who sends them the work.
Should I call my insurance company or a restoration company first? Most of our customers call their insurance company first to confirm their coverage. When you do, ask whether your policy lets you choose who does the mitigation, and what your coverage is if you do.
Is Affordable Water and Mold Removal on any insurer’s preferred vendor list? No. We never have been. We work for you, the homeowner.
Why Brevard homeowners call us
We’re a small-town company, and we’re proud of our Brevard roots. We treat our customers like family, not like a number, and we take care of every home like it’s our own. We’ve never worked for an insurance company. On a claim, we work for you, the homeowner, because working for the insurer too would be a conflict of interest. We aim to do it right the first time, so you shouldn’t need to call us back unless something new happens. And honestly, we just like making a bad day a little better, even if it’s only by lending a hand.
Call Affordable Water and Mold Removal at (321) 890-2512 for a free moisture evaluation. We serve all of Brevard County, from Mims to Palm Bay and the beaches.
About the author: Daniel Ryan Townsend grew up in Port St. John and has spent 15+ years in the restoration field, starting in his early twenties as a helper for a Brevard County restoration company. He worked his way up from technician to lead tech, supervisor, and management, then opened Affordable Water and Mold Removal in March 2018. He has been IICRC certified for 10+ years and holds the WRT (water damage restoration) and AMRT (mold remediation) certifications, plus Florida mold remediator license MRSR3317.
Recent Posts
Water Behind a Bathroom Vanity: Rockledge Water Damage Mitigation, Before and After
The vanity in this Rockledge bathroom looked normal from the front. The wall behind it did not. Here is how the job went, from floor protection to a dry wall.
The AC Drained Into the Garage Ceiling: Melbourne Mold Remediation, Before and After
An upstairs AC drain line backed up in a Melbourne home and the water ended up in the garage ceiling. Here is the mold we found, the tear-out and the clean result.
Mold From a Failing AC: Titusville Humidity Mold Remediation, Before and After
No leak, no flood. A malfunctioning AC let the indoor humidity climb in this Titusville home until mold started growing. Here is the cleanup.